Intuit Credit Karma
Credit Karma, LLCFinanceVerified
- 441.45K Reviews
- 4.7
- Downloads
- 50,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When I want a quick read on my credit without turning it into a full evening of paperwork, I open Intuit Credit Karma. I find it most useful as a regular check-in: it brings credit information, report changes, and suggestions into one place, then gives me a reason to investigate anything that looks unfamiliar. It is a free finance app from Credit Karma, LLC, and its large community—over 50 million installs and a 4.7 average from around 3.1 million ratings—suggests it has become a familiar starting point for people keeping an eye on their credit.
Getting Started with Ease
First things first, setting up Credit Karma is a breeze. You just download the app, punch in some basic info, and voilà! You’re in. The interface is super user-friendly, which is a huge plus if tech isn’t really your thing. I was pleasantly surprised by how intuitive everything felt from the get-go. It is rated for Everyone, and the app has been available since February 28, 2013; version 26.4 supports devices running Android 9 or later. Those details make it easy to judge whether it fits your device and household, but I would still use a secure screen lock and avoid checking sensitive account information on a shared device.
A steady baseline, not a one-time score check
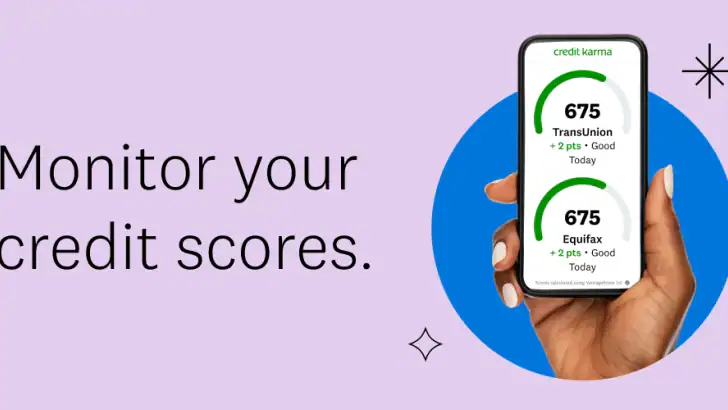
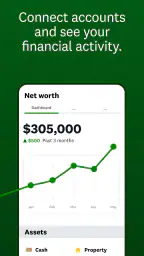
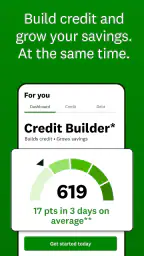
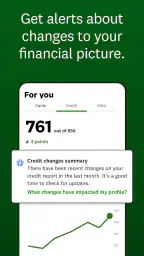
Now, let’s talk features. This app doesn’t just give you your credit score and call it a day. Oh no, it goes way beyond that. You get a deep dive into your credit report, complete with nifty graphs and breakdowns that make it easy to understand what’s affecting your score. And if you’re anything like me, visual aids are a lifesaver. The practical benefit is not that a graph makes every financial decision for you; it helps you spot what deserves a closer look and gives you a more approachable route into a report that can otherwise feel dense.
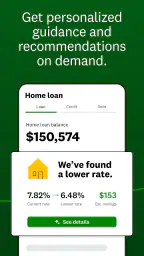
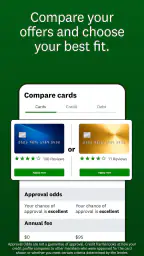
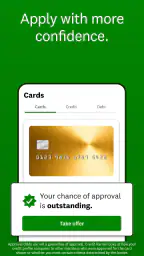
Another cool feature? The personalized recommendations. Based on your profile, the app suggests credit cards and loans that could be a good fit for you. It’s like having a personal shopper, but for credit. I found this super helpful, especially when I was considering getting a new card. I treat those suggestions as options to research, rather than instructions to apply. Before acting, I would compare the terms that matter to my situation and consider whether opening another account fits my plans. A recommendation can make the search less overwhelming, but it cannot decide whether a new borrowing commitment is sensible for you.
For a realistic routine, imagine checking the app before planning a major purchase. I would first look for changes in the report, then note any item I do not recognize, and only after that consider whether a product suggestion is relevant. That order matters: it separates monitoring from shopping and makes it less likely that an attention-grabbing offer distracts me from a report detail I meant to investigate. If everything looks familiar, I can close the app without feeling that I need to take action just because a recommendation is available.
Alerts and Notifications
The alerts system is another gem. You’ll get updates on any changes to your credit report or score, and trust me, staying informed is half the battle. This feature alone takes a load off your shoulders because you’re not left in the dark about your financial health. I see alerts as prompts to review, not as a verdict about whether a change is good or bad. If one appears, opening the relevant report information and checking whether it matches something I recognize is a more useful response than reacting to the headline alone.
Plus, they throw in some handy tips and advice to help you boost your score. It’s like getting free financial advice without having to sit through a boring workshop. Who doesn’t love that? I get the most value by turning a tip into one small, repeatable check rather than trying to overhaul my finances all at once. For example, I can read the explanation, decide whether it applies to my circumstances, and revisit the same part of my report later. That makes the educational side feel more practical, while leaving room for the fact that personal finances rarely follow a one-size-fits-all script.
Other Stories to Read




Settings that make checking feel manageable
I would take a moment after setup to decide how much interruption I actually want from notifications. Credit updates are useful, but constant phone alerts can become background noise; if I start dismissing them automatically, they stop helping. Keeping the alerts I am likely to act on and checking the app at a regular time is a better balance for me than opening it every time I pick up my phone. The exact choices available can depend on the app and device, so I would review the controls shown in my own version instead of assuming every setting is identical.
I also recommend making the first report review a baseline. Rather than trying to memorize a score, I would note the accounts and details I recognize, then use later checks to notice what has changed. If an unfamiliar item appears, I would avoid guessing at its meaning from a chart alone. I would inspect the relevant report information and use the appropriate follow-up process for the issue. This habit turns the app into a monitoring tool instead of a source of vague reassurance or unnecessary alarm.
Faster patterns for repeat visits
Once I know where the report, score information, and recommendations sit in the app, I can give each visit a purpose. A quick check can be for a new alert; a longer one can be for reviewing report details or comparing possible products. That simple distinction saves time and keeps me from wandering between screens without knowing what I came to do. I would also avoid treating every suggested product as a task. If I am not actively considering borrowing, there is no reason to turn browsing into an application decision.
A useful rhythm is to check after a notification, then do a calmer review at a time when I can concentrate. If the alert raises a question, I can write down the detail I need to verify instead of repeatedly reopening the same screen. For someone preparing to apply for credit, the app can help organize what to inspect beforehand; it is not a substitute for reading a lender’s own terms or checking the details required by that lender. Separating those jobs keeps the app useful without expecting it to be the whole financial process.
Where the convenience has limits
The main trade-off is that a simple interface can make complicated credit decisions look more straightforward than they are. A score is only one part of a broader picture, and a product suggestion is not a personal financial plan. I would not use a credit-monitoring app alone to decide whether I can afford a loan, settle a disputed report item, or choose between offers with different terms. Those decisions need closer reading and, where appropriate, help from the relevant institution or a qualified adviser.
It is also worth remembering that a notification tells me to look, not necessarily what caused a change or what action is best. If an entry seems wrong, I should verify the details and follow the proper route to address it rather than assuming the app can resolve every issue on my behalf. And if I simply want to manage spending and transactions, a budgeting app or the tools provided by my bank may be a better fit. Credit Karma is centered on credit awareness and related suggestions, not a replacement for every kind of money-management tool.
Who will get the most from it
I think the app suits people who want a low-friction way to check their credit information, understand report changes, and explore possible credit products without starting from a blank search. It is especially handy if you are building a habit of reviewing your credit or want a visual overview before doing more detailed research. With 441,000 reviews and more than 3.1 million ratings, it is clearly widely used, but popularity does not remove the need to decide whether its focus matches your own needs.
Someone who prefers to keep all financial activity inside a bank’s own app may find that existing tools are enough, especially if they mainly want balances, transactions, and spending categories. Likewise, if you do not want product recommendations mixed into a credit check, you may prefer to consult a credit-reporting service for monitoring and research products separately. I would skip Credit Karma as a primary tool if what I really need is a detailed household budget, bill scheduling, or a complete view of cash flow; those are different jobs from understanding credit.
Security and Peace of Mind
I know, I know, putting your financial info into an app can be nerve-wracking. But rest easy because Credit Karma takes security seriously. They use bank-level encryption to keep your data safe, which honestly, is a relief. It’s nice knowing that my sensitive info isn’t floating around in cyberspace. Even so, I would keep my own basic precautions in place: use a strong device passcode, avoid sharing a logged-in phone, and take care when reviewing personal details in public. Security features are reassuring, but they are not a reason to be careless with access to a device.
Final Thoughts
So, is Credit Karma worth a download? Absolutely. It’s packed with features that make managing your credit not just possible, but downright enjoyable. The insights you gain are invaluable, especially if you’re planning on making big financial moves. Plus, it’s free. Yes, you heard me right, free! So why not give it a shot and see how it can help you take charge of your credit health? My more measured recommendation is to use it as a convenient starting point and keep your own judgement in charge. The app is strongest when it helps me notice, understand, and follow up—not when I expect a score or a product suggestion to settle a complicated decision for me.
If you’re ready to dive in and take control of your financial future, you can grab the app from your preferred app store and start exploring what Credit Karma has to offer. Trust me, you’ll be glad you did. I would begin with a report review, choose a notification routine I can sustain, and return when there is a clear reason to check. That gives the app a practical role in my financial habits while keeping its recommendations in perspective.
Highlights
- User-friendly interface for easy navigation.
- Comprehensive credit score monitoring tools.
- Free access to credit reports and scores.
- Personalized financial recommendations offered.
- Secure and private data handling practices.
Limitations
- Limited support for non-U.S. users.
- Occasional ads can be distracting.
- Credit scores may vary from other services.
- Limited access to customer support options.
- No direct credit repair services available.
Frequently Asked Questions
01What features does Intuit Credit Karma offer?
Intuit Credit Karma provides free credit scores, reports, and monitoring. It offers personalized recommendations for credit cards and loans, tools to simulate credit score changes, tax filing services, and identity theft protection. The app's user-friendly interface makes it easy to navigate these features, allowing users to better manage their financial health.
02Is Intuit Credit Karma safe to use?
Yes, Intuit Credit Karma is safe to use. The app employs advanced encryption and security measures to protect users' personal and financial information. Additionally, it does not share your credit scores or reports with third parties without your consent, ensuring your privacy is maintained.
03Does using Intuit Credit Karma affect my credit score?
No, using Intuit Credit Karma does not affect your credit score. The app performs a 'soft inquiry' to access your credit information, which does not impact your score. This allows you to check your credit health frequently without any negative consequences to your credit rating.
04How accurate are the credit scores provided by Intuit Credit Karma?
The credit scores provided by Intuit Credit Karma are accurate but may differ slightly from those used by lenders. The app provides scores based on the VantageScore 3.0 model using TransUnion and Equifax data. While these scores are reliable, lenders might use different models or data sources.
05Is Intuit Credit Karma available for both Android and iOS devices?
Yes, Intuit Credit Karma is available for both Android and iOS devices. Users can download the app from the Google Play Store or Apple App Store. It offers the same functionalities across both platforms, ensuring a consistent user experience regardless of the device you use.


